Cristina Acosta
Mortgage Associate · English, Español
Newcomers on work permits or PR, first-time buyers, renewals and refinances.
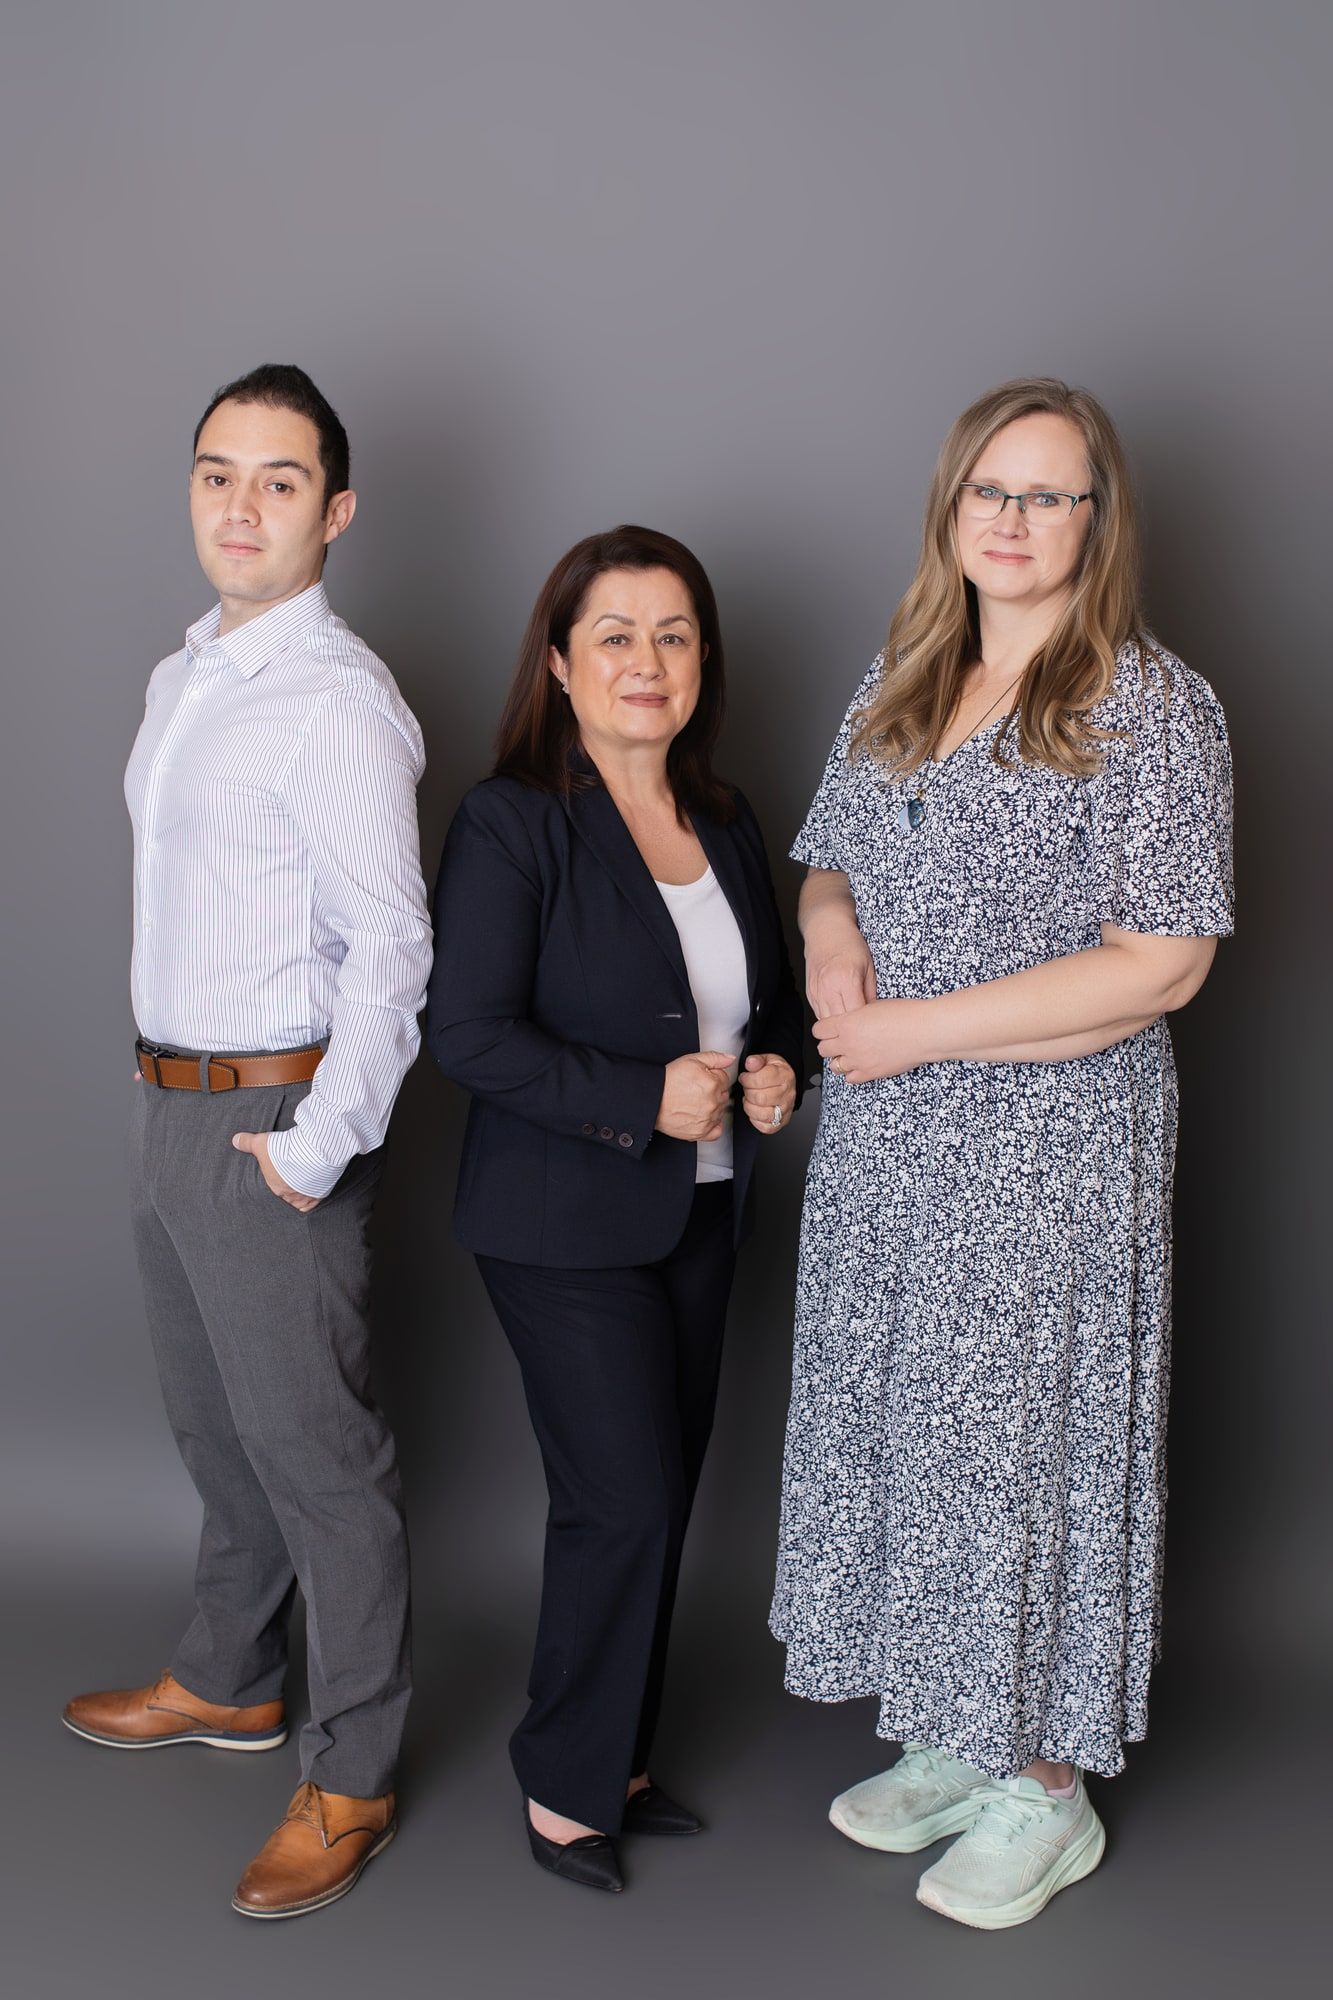
Three licensed Mortgage Associates who plan the mortgage around your life, then walk you through every document, condition and decision until the keys are in your hand.
Here is how it goes for first-time buyers. Choose a different situation above and the steps change with it.
What you can afford, honestly, before you fall for a listing.
Down payment, credit and the programs you qualify for.
Your options across lenders, not one bank’s menu.
A pre-approval you can shop with.
Conditions explained line by line.
Lawyer, realtor and lender coordinated to your closing date.
Your first renewal, planned from day one.
Every mortgage we arrange starts with one of these. If yours is not here, it is in the full list, from bridge financing to spousal buyouts.
Down payment, programs, pre-approval and what happens after your offer is accepted.
See the stepsWork permit, PR or citizen: which lenders accept your status and your income history.
See the stepsYour tax return is not your income. We show lenders the business behind it.
See the stepsYour renewal letter is an offer. We check it against the market before you sign.
See the stepsDebt consolidation, renovations, a second property: the cost of each way to use your equity.
See the stepsCash flow first, then the property. Rental income rules by lender.
See the stepsWe assess the file and coordinate with commercial specialists when the deal calls for one.
See the stepsBridge, purchase plus improvements, spousal buyout, reverse, construction, rural, non-resident, switch, second opinion and more.
See the full listMove the sliders. The number updates as you go, including mortgage insurance when the down payment is under 20%.
Estimate only, not an offer of credit. Excludes property tax, insurance and condo fees. Constants verified 2026-09-16.
A bank appointment is a race against the clock. Ours ends when your questions do.
Most people can only deal with a mortgage after work. So that is when we work.
Sometimes the honest advice is not to buy yet. We would rather earn a client next year than a deal today.
We know what a Canadian lender needs to see from a foreign income history, because we have lived it.
A bank sells its own shelf. We have access to 249 lenders through Mortgage Alliance, so the file goes where it fits.
Every update, every condition, every next step, explained before you have to ask.
Choose whoever fits your situation or language. You get the same process, the same honesty and the same answers on a Sunday morning.
Mortgage Associate · English, Español
Newcomers on work permits or PR, first-time buyers, renewals and refinances.
Mortgage Associate · English, Español
First-time buyers, self-employed income, and files a bank has already declined.
Mortgage Associate · English
First-time buyers, self-employed professionals, refinancing and home equity.
Tell us the month. Ninety days before it, we check what your lender offers against the whole market and send you the comparison. No obligation, no forms until then.
Income, down payment, credit, ID and the documents lenders ask for, in the order they ask.
Read the guideBefore you buyLegal fees, title registration, appraisal, adjustments and what to have in cash on closing day.
Read the guideOwning and renewingWhy the first offer is rarely the best one, and how switching works without a lawyer.
Read the guideChoose who you would like to talk to, then how. A first conversation costs nothing and commits you to nothing.
Newcomers on work permits or PR, first-time buyers, renewals and refinances.
English · Español
First-time buyers, self-employed income, and files a bank has already declined.
English · Español
First-time buyers, self-employed professionals, refinancing and home equity.
English